Professional Indemnity Insurance for Consultants
Protects consultants when flawed advice causes client losses

Policy Provided By
Professional Indemnity Insurance for Consultants
Protects consultants when flawed advice causes client losses
Get Quotes in a Few Steps

Currently Reading
1. What Is Professional Indemnity Insurance for Consultants?
2. Type of Consultants That Need This Cover
3. How Engagement Letters Create PI Exposure?
4. What Does PI Insurance Cover for a Consultant?
5. Why a Gap in Your Policy Can Void Past Engagements?
6. What the Policy Does Not Cover?
7. What Affects the PI Premium for Consultant?
8. How to Buy Professional Indemnity Insurance for Consultants From BimaKavach?
Professional indemnity insurance for consultants pays the legal fees and the compensation your firm becomes liable for when a client claims that your advice, your deliverables, or your project management caused them a financial loss.
Most management consultants operate under a comfortable assumption: since the client makes the final decision, the consultant who only advised cannot be held liable for the outcome. That assumption is wrong. Under the Hedley Byrne principle, adopted into Indian jurisprudence through multiple High Court and Supreme Court decisions, a professional who gives advice owes a duty of care to anyone who reasonably relies on it. The client who followed your strategy recommendation and lost money does not need to prove you made the decision for them. They only need to prove they relied on your advice and that the advice fell below the standard of care expected of a competent consultant.
The exposure and sizing of PI cover depend on what kind of consulting you do and who your clients are. Five domains carry the highest liability.
Management and Strategy Consultants
A market entry strategy that leads a client into a loss-making geography, a restructuring plan that triggers regulatory scrutiny, or a pricing recommendation that erodes margin all trace back to the consultant's advice. Enterprise clients routinely require PI cover as a condition in the engagement letter before work begins. The claim is not capped by what you charged for the project; it is sized by what the client lost by following the advice.
IT and Technology Consultants
Recommending a platform that later fails, advising on a cloud migration that causes data loss, or designing a technology architecture that cannot scale all produce professional liability claims. IT consultants who handle client systems also face exposure under the DPDP Act, 2023 for mishandling personal data during implementation. If the client's system goes down because of your technical recommendation, the claim lands on you, not on the vendor you recommended.
Finance, Tax, and Transaction Advisory Consultants
Consultants who advise on mergers, acquisitions, valuations, or tax structuring face claims not just from the direct client but from third parties who relied on the advisory output. A lender who advanced funds based on your valuation, an investor who committed capital based on your financial model, or a tax authority that challenges a structure you recommended can each bring a claim. The Hedley Byrne duty of care for negligent misstatement extends liability beyond your direct client.
HR and Recruitment Consultants
Recommending a candidate who turns out to have fabricated credentials, advising on a compensation structure that violates labour law, or mishandling employee data during an organisational redesign can each produce a claim. The Digital Personal Data Protection Act, 2023 now holds anyone processing personal data directly accountable, including HR consultants who handle employee records on behalf of a client.
Operations and Supply Chain Consultants
A process redesign that increases defect rates, a vendor selection recommendation that leads to supply chain failure, or an inventory optimisation model that causes stockouts all create professional liability exposure. The claims tend to be large because the financial impact of an operations failure compounds across the client's production cycle.
Most consulting firms treat the engagement letter or MSA as their primary risk management tool. The limitation of liability clause, the cap on damages, and the indemnity terms are negotiated carefully. But three common contract features work against the consultant rather than for them.
1. Unlimited Liability Carve-Outs for Negligence:
Government procurement rules, including the Ministry of Finance Manual for Procurement of Consultancy Services, prescribe that broad liability caps are not permitted in central government engagements. Even in private-sector contracts, limitation clauses are enforceable only within reasonable bounds under the Indian Contract Act (Sections 23, 73, and 74). Courts routinely strike down caps on gross negligence or wilful default. The engagement letter's liability cap is a negotiating tool, not a guarantee. PI insurance is the financial backstop when the cap does not hold.
2. Indemnity Clauses That Run to Third Parties:
Many enterprise MSAs include a clause requiring the consultant to indemnify the client against third-party claims arising from the consultant's work. A lender, an investor, or a regulator who claims reliance on the consultant's output can trigger the indemnity, and the consultant bears the cost. The Hedley Byrne duty of care means the consultant's exposure extends beyond the direct client to anyone who reasonably relied on the advice.
3. Warranty of Accuracy in Deliverables:
Standard consulting MSAs include a warranty that the deliverables will be prepared with reasonable skill and care. When a client claims the deliverable contained inaccurate data or flawed analysis, the warranty clause is the legal hook. The claim is not for breach of a commercial guarantee (which would be excluded); it is for breach of the professional standard of care, which is exactly what PI insurance covers.
The PI premium is fully deductible as business expenditure under Section 37(1) of the Income Tax Act, 1961. For consultants in the 30% tax bracket, the after-tax cost of the premium is 25-30% lower than the sticker price.
The policy funds the cost of defending the claim and the compensation owed if your firm is found liable.
Flawed Strategic and Management Advice:
The client implemented your recommendation and suffered a financial loss. Whether it was a go-to-market strategy, an organisational redesign, or a technology selection, the policy covers the claim for the loss your professional advice caused.
Negligent Misrepresentation and Scope Drift:
You presented findings or projections that turned out to be materially inaccurate, or the project scope expanded beyond the original terms and the expanded work caused a loss. Where the misrepresentation was unintentional and made in the course of professional work, the policy responds.
Breach of Client Confidentiality:
Sensitive business information the client shared during the engagement was disclosed to a third party, whether through employee negligence, an unsecured document, or a system error. The policy covers the client's claim for the financial loss the disclosure caused.
Legal Defence and Settlement Costs:
Every covered claim includes the cost of legal representation, from the first legal notice through to final disposal. Court attendance costs, advocate fees, and settlement amounts are all covered up to the sum insured, whether the claim succeeds or not.
PI policies work on a claims-made basis. The policy that responds is the one in force when the claim is first reported to the insurer, not the one that was active when the advice was given or the project was delivered.
The retroactive date sets how far back the policy reaches. Work completed before that date falls outside the cover. On a first-time policy, the retroactive date is usually the inception date, so past projects are not covered on day one.
Here is a scenario that catches consulting firms. Your team delivers a strategy engagement in March. You buy your first PI policy in July with the retroactive date set to 1 July. Two years later, the client discovers the strategy was built on flawed market data your team provided, and the resulting loss runs into crores. The policy is live, you notify in time, but the project finished before the retroactive date. The insurer declines the claim.
Three protections belong in the policy from the start:
- Run-Off Cover: Protects the firm for past work after the founding partner exits or the practice dissolves.
- Extended Reporting Period (ERP): A window after the policy ends to notify claims about work done during the policy term.
- Wider Retroactive Date: Pushed back to when the practice started, available after several continuous years with a clean claims record.
Commercial Guarantees on Revenue or Profit:
If you guaranteed a specific revenue outcome or profit target in your engagement letter and the client did not achieve it, that is a contractual warranty, not professional negligence. The policy does not cover guarantees of commercial results.
Intentional Misrepresentation or Fraud:
Knowingly presenting false data, fabricating qualifications, or deliberately misleading a client is excluded once established by a court or tribunal. The policy still covers the legal defence costs until that finding is made.
Bankruptcy and Insolvency Advice Liability:
Claims arising from advice on insolvency proceedings or bankruptcy restructuring are typically excluded under a separate carve-out. Consultants advising distressed companies should check whether this exclusion applies and whether a separate policy covers that work.
Known Claims and Prior Circumstances:
Any matter you were aware of when buying the policy, or any claim already notified under a prior policy, is excluded. Disclose everything on the proposal form.
- Annual Fee Income: The starting point for every quote. Higher fee income means more client work at risk.
- Consulting Domain: Transaction advisory and due diligence work attract higher rates than general management consulting because the single-claim severity is larger and third-party reliance is more common.
- Client Geography: Serving US or EU clients raises the premium because those jurisdictions have higher litigation frequency and larger damage awards.
- Number of Consultants: More professionals delivering advice means a larger surface for professional error.
- Claims History: Any prior claim or disclosed circumstance increases the rate. A clean record over several years earns a discount.
BimaKavach is an IRDAI-registered platform. The buying process runs online and takes minutes.
| 1. Get Instant Quotes: | 2. Choose Your Coverage and Insurer: | 3. Pay Online and Get Your Policy: |
|---|---|---|
| Enter your consulting domain, annual fee income, and team size. Quotes from multiple insurers appear within seconds. | Our experts walk you through the retroactive date, run-off options, and limits so the policy matches your engagement portfolio. | Complete payment digitally and receive policy documents within minutes. |
Step by Step Process to Get PI Policy Through BimaKavach
1. Get Instant Quotes:
Enter your consulting domain, annual fee income, and team size. Quotes from multiple insurers appear within seconds.
2. Choose Your Coverage and Insurer:
Our experts walk you through the retroactive date, run-off options, and limits so the policy matches your engagement portfolio.
3. Pay Online and Get Your Policy:
Complete payment digitally and receive policy documents within minutes.
Documents You Will Need:
- Completed proposal form
- Firm KYC (partnership deed, LLP agreement, or sole proprietorship PAN and GST details)
- Annual fee income for the most recent financial year
- Details of consulting domains and client geographies served
- Sample engagement letter or MSA (to assess liability terms)
- Claims history, if any
Professional Indemnity Insurance, for Every Kind of Business
Professional Indemnity Insurance
Protects professionals if their work causes loss or damage to clients
For Chartered Accountants
Protects CAs when audit or filing errors cause claims
For Lawyers
Protects lawyers when legal errors cause client losses
For IT Companies
Protects IT firms when software failures or breaches cause damage
For Architects
Protects architects when design errors cause project disputes
For Engineers
Protects engineers when technical errors cause project failures
Trusted by India's Top Businesses
A new experience.
Built on intelligence. Covered in minutes.
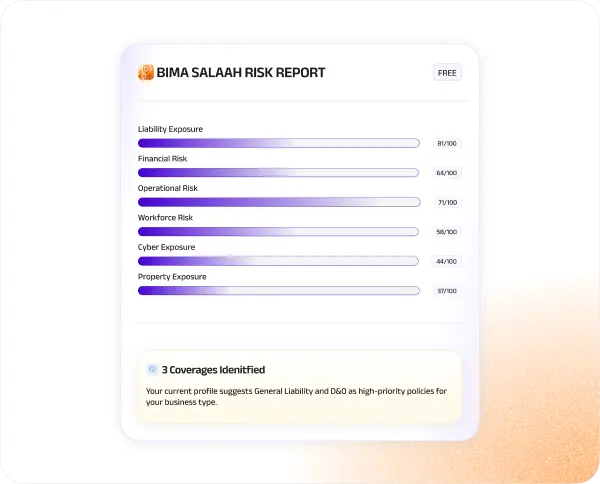
Every risk, read instantly.
Everything your business is exposed to, analysed before any cover is placed.
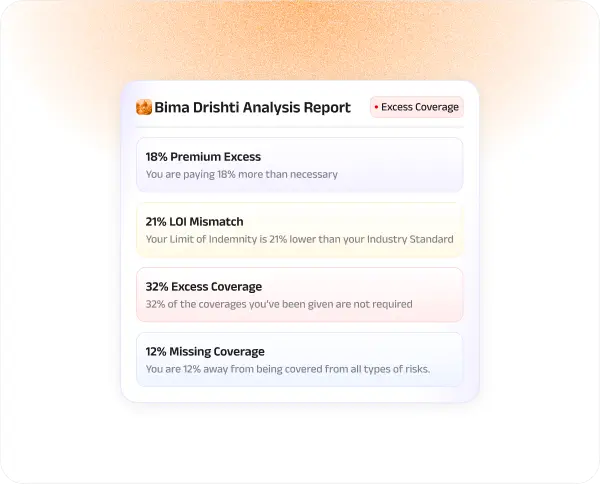
Every gap, caught early.
The gaps your current cover leaves open, surfaced before they turn into a claim.
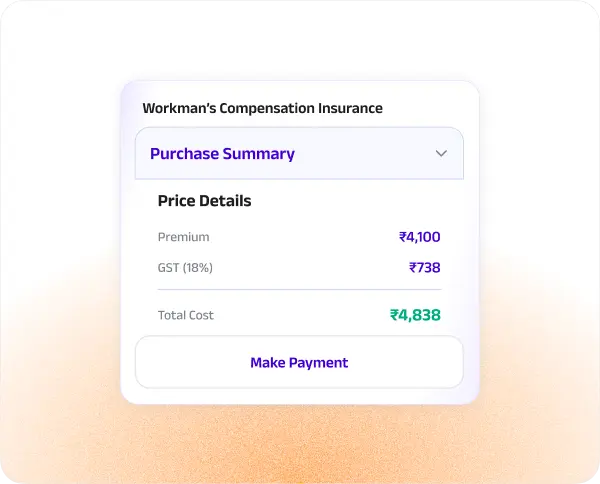
Right coverage, issued in minutes.
The right cover, priced and placed with India's top insurers, in minutes.
India's builders trust BimaKavach.

Learn More About
Professional Indemnity Insurance for Consultants
Professional Indemnity Insurance for Consultants, made Simple
Yes. Under the Hedley Byrne principle, adopted into Indian law, a professional who gives advice owes a duty of care to anyone who reasonably relies on it. The client does not need to prove the consultant made the decision. They only need to prove they relied on the advice and that it fell below the standard expected of a competent consultant. The "advisory-only" defence does not hold up in court.
There is no single professional body that mandates it. But the practical requirement comes from enterprise clients who will not sign an engagement letter without proof of cover, and from government procurement rules that prescribe PI as a condition in consultancy contracts. The DPDP Act, 2023 adds a regulatory layer: any consultant processing client data is now personally accountable for mishandling it, regardless of whether a professional body exists.
If the scope expanded beyond the original terms and the expanded work involved professional negligence that caused a loss, the policy typically responds. If the dispute is purely commercial, where the client is unhappy with the scope but no professional error occurred, that is a contractual matter outside the PI policy.
Identify your largest single-engagement exposure. The IRDAI 25% AOA rule means the per-claim cap is one-quarter of the annual aggregate. If your largest engagement could produce a Rs 1 crore claim, the annual sum insured needs to be at least Rs 4 crore so that 25% of it covers the single claim. Our advisors help you size both limits against your actual engagement portfolio.
Yes, where the third party reasonably relied on your professional work. A lender who advanced funds based on your due diligence report, or an investor who committed capital based on your market assessment, can bring a claim. The Hedley Byrne duty of care extends the consultant's exposure beyond the direct client.
Exclusive Cyber Risk Assessment
Bima Netra
 Instant Cyber Risk Report
- Actionable Posture Insights